The Freelancer's Guide to Malta Tax, VAT and Expenses
When you work for yourself in Malta, nobody deducts tax from your pay for you. This guide sets out the VAT registrations, provisional tax, reduced rates and social security that MTCA describes for the self-employed, so you know what to ask your accountant.
Updated 2 November 2026 · 6 min read
Everything below is what the official pages said at the time of writing (November 2026). Rates and thresholds change, and your own mix of income matters. Use this guide to prepare your questions, not to file your return.
The basics: tax number and what is taxed
Tax and VAT for freelancers are handled by the Malta Tax and Customs Administration (MTCA). You also register your self-employment with Jobsplus, which our guide to starting freelancing covers step by step.
Maltese citizens and residents normally use their identity card number as their tax number. Foreigners living in Malta register as taxpayers and are given a 9-digit tax number. A person who is resident and domiciled in Malta is taxed on worldwide income, including income from a trade, business or profession carried on in Malta or abroad.
SourceWhich VAT registration fits you
MTCA lists three VAT articles that a self-employed person can register under, and you can fall under more than one. The choice changes whether you add VAT to your invoices and whether you can recover VAT on what you buy.
| Registration | Who it is for | What it means for your invoices and costs |
|---|---|---|
| Article 10 | Anyone supplying taxable goods or services in Malta, exporting goods outside the EU, or supplying goods or services that take place in other EU states | You charge VAT and can claim input VAT on purchases linked to your supplies |
| Article 11 | Small undertakings that qualify under the Sixth Schedule of the VAT Act | You do not charge VAT and cannot claim back VAT on your costs |
| Article 12 | People not under Article 10 who buy services from suppliers outside Malta where the VAT is due in Malta and the customer pays it, or who buy goods from other EU states above a yearly limit | You account for the VAT on those purchases yourself |
MTCA says self-employed people registered under Article 11 cannot charge VAT to customers or claim input VAT on purchases, even business ones, and are treated as exempt from VAT.
SourceSince 1 January 2025, you qualify for Article 11 only if your domestic annual turnover (sales taking place in Malta, excluding VAT, in a calendar year) stays within the domestic threshold in the law. If turnover goes over the threshold during the year, you have to move to an Article 10 registration. Check the current threshold in MTCA's notes.
SourceAt the time of writing (November 2026), the standard VAT rate in Malta is 18%, with reduced rates of 5% and 7% for some goods and services.
SourceIf most clients are VAT-registered businesses, or you buy expensive equipment, being able to recover VAT can matter more than keeping prices VAT-free. Ask an accountant to compare both before you choose.
Provisional tax: paying during the year
Self-employed income is taxed in the year you earn it, through provisional tax payments, and settled when you file your return.
MTCA says provisional tax is due from every individual who must submit an income tax return and self-assessment. If your income falls, you can ask to pay less with a Provisional Tax Reduction Form, on paper or through MTCA My Account.
SourceMTCA's provisional tax booklet sets three due dates for individuals: 30 April, 31 August and 21 December. By those dates you pay at least 20%, a further 30% and a further 50% of your benchmark, which is normally the tax from your self-assessment two years earlier. These are the dates at the time of writing (November 2026).
SourceBecause the benchmark looks back, a fast-growing income can leave a larger balance to pay when you file. Move a share of every payment you receive into a separate account, so the bill is never a surprise.
Part-time and creative income
At the time of writing (November 2026), part-time self-employment can be taxed at a flat 10% of net profit, up to a yearly cap, if you also work full-time, are a pensioner or are a full-time student or apprentice. You must register the part-time work with Jobsplus, have no more than two employees in it (part-time only), work for someone other than your full-time employer, register for VAT if obliged to, and pay with form TA22 by 30 April of the following year.
SourceThe 10% tax is final, so that income does not need to go on your annual return. Profit above the cap is declared in the return and taxed at the normal rates. A married person who only works part-time can still qualify if their spouse works full-time, is a pensioner or is a student.
SourceWith form TA26, a self-employed person can opt to pay a final 7.5% tax on income from an artistic activity, from basis year 2026 and up to a yearly ceiling. Arts Council Malta must certify the activity, and payment is due by 30 April of the following year. Late payments carry interest of 0.6% a month. These are the terms at the time of writing (November 2026).
SourceSocial security as a freelancer
Class 2 contributions are paid by people who earn more than a yearly threshold from an economic activity and are not employed. The law separates self-occupied persons (income from a trade, business or profession) from self-employed persons (income from rents, investments or capital gains). Rates are based on your net profit or income for the year before the payment year.
SourceIf you have a job and freelance on the side, how Class 1 and Class 2 apply to you depends on your situation. That is a good first question for your accountant.
Sales, invoices and expenses
Good records make every part of this cheaper. Your accountant can only claim what you can prove, and tidy files take less of their time. Keep business money in its own bank account and file paperwork as it arrives, not in April.
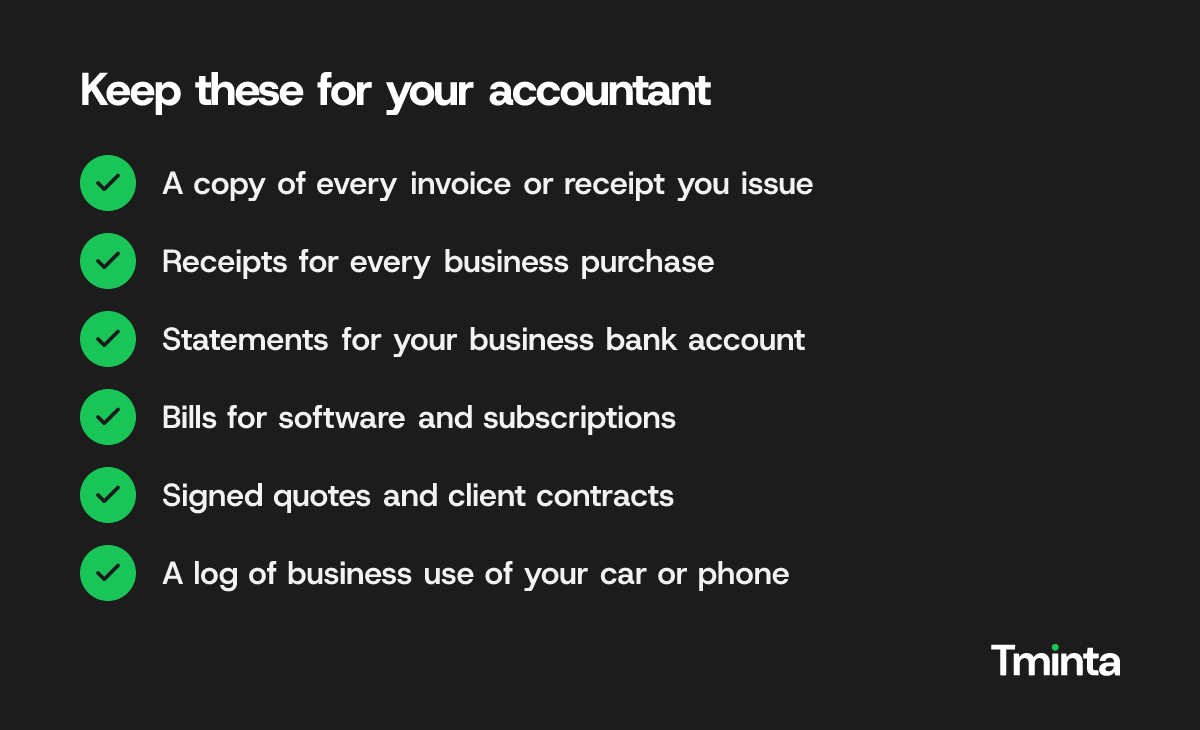
- Ask your accountant what each invoice must show under your VAT registration, and use one numbered sequence.
- Ask which costs you can deduct, such as equipment, software, a share of your phone bill or a workspace at home.
- Ask whether subscriptions you pay to foreign suppliers mean you need an Article 12 registration.
- Ask what your deadlines are for VAT returns and the income tax return, and put them in your calendar.
Get help, and get found
A yearly fee to a professional often costs less than one missed deadline. Compare tax accountants who work with sole traders, and ask each one which returns their fee covers. When your own business is ready for clients, list your business on Tminta for free.
Questions people ask
Do freelancers pay tax in Malta?
Yes. Income from self-employment is taxable. During the year you normally pay provisional tax in three instalments, then settle the balance through your tax return. Some people qualify for a reduced, final rate on part-time self-employment or certified artistic income. You may also owe Class 2 social security. An accountant can tell you which applies.
Do I have to register for VAT as a freelancer in Malta?
Jobsplus says that once you register as self-employed you will also need a VAT number. MTCA offers registration under Article 10, 11 or 12, depending on what you sell, how much you sell in Malta and what you buy from abroad. Which one fits changes what you charge and what you can reclaim.
What is the VAT rate in Malta?
At the time of writing (November 2026), the standard rate is 18%, with reduced rates of 5% and 7% for some goods and services. If you are registered under Article 11, you do not add VAT to your invoices at all. Check the rate for each service you sell with an accountant.
When do self-employed people pay tax in Malta?
MTCA's provisional tax booklet gives 30 April, 31 August and 21 December as the instalment dates for individuals, paying 20%, 30% and 50% of the benchmark. The part-time 10% and creative 7.5% payments are due by 30 April of the following year. Confirm current deadlines on mtca.gov.mt before you pay.